
The Food and Agriculture Organization (FAO) forecasts global cereal production at 2.979 billion tonnes in 2026, 2.1% below the previous year’s record but still the second-highest harvest on record. Global cereal stocks are projected to reach approximately 950 million tonnes at the end of the 2026-27 season.
Yet the FAO Food Price Index averaged 136 points in September, up 1.5% from August and 5.8% year-on-year, highlighting the disconnect between aggregate grain availability and food affordability.
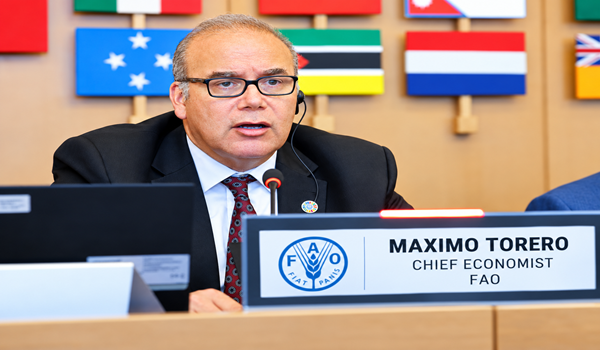
FAO Chief Economist Máximo Torero has warned that sustained increases in global commodity prices could feed through to consumer food prices, particularly in countries dependent on food and energy imports. External Affairs Minister S Jaishankar has also cautioned about the possibility of a major food crisis in the coming months.
Geopolitical tensions raise supply chain costs
The conflict triggered by US-Israeli strikes on Iran on February 28, 2026, has disrupted energy markets and shipping through the Strait of Hormuz, a key route for global oil and fertiliser trade.
By April, oil tanker freight rates had increased by more than 90%, bunker fuel prices had nearly doubled and war-risk insurance premiums had surged, raising the cost of transporting commodities.
International fertiliser prices have also climbed. According to the World Bank, urea prices rose 80% between February and April to more than $850 a tonne, while diammonium phosphate prices increased by over 10% in April.
Disruptions in the Black Sea region have added to concerns over grain availability. The FAO’s Cereal Price Index increased 5.1% in September from the previous month and stood 17.2% higher than a year earlier. International wheat prices rose 6.3% during the month, partly because of logistical constraints in the Black Sea and dry weather in parts of North America ahead of planting.
Maize prices increased 5.6%, reflecting lower-than-expected US yields, reduced export availability in Brazil and disruptions to Black Sea trade. International sugar prices rose 6.1%, while the FAO Vegetable Oil Price Index gained 0.9%, supported by higher palm oil prices and strong import demand.
These developments demonstrate why large grain inventories cannot fully protect consumers from inflation. Food prices also reflect the costs of fuel, fertilisers, processing, storage, insurance and transportation.
El Niño threatens the 2027 harvest
Weather uncertainty is emerging as another risk to agricultural production. The US National Oceanic and Atmospheric Administration’s October 8 assessment indicated that a strong-to-very-strong El Niño was likely to persist through January-March 2027, with the probability remaining above 83%.
El Niño does not automatically lead to widespread crop failures. Its impact varies by region and crop, with some areas facing drought and others experiencing excessive rainfall. However, the FAO has identified parts of South and Southeast Asia, Southern Africa, the Sahel and Central America as vulnerable to drought.
India has already experienced uneven rainfall. According to the India Meteorological Department, the 2026 southwest monsoon ended with rainfall 13% below normal, the lowest level since 2015. Southern peninsular India recorded a 24% deficit, while East and Northeast India received 26% less rainfall than normal.
Lower soil moisture, reduced water availability and higher irrigation costs could affect the next planting season. If farmers also face expensive or delayed fertiliser supplies, crop yields could come under further pressure.
The timing of these risks is significant. Higher input costs can influence farmers’ decisions on how much fertiliser to apply, which crops to plant and how much acreage to cultivate. Any resulting decline in yields could tighten supplies during the 2027 harvest cycle.
India’s grain stocks offer a buffer, but food inflation persists
India’s experience illustrates why food security cannot be measured by grain stocks alone. The country has substantial reserves of wheat and rice, but remains exposed to international energy, fertiliser and edible oil prices.
According to the Petroleum Planning and Analysis Cell, India’s crude oil import bill rose 48.4% year-on-year to $74.8 billion during April-August 2026, even as import volumes declined marginally.
Commerce Ministry data show that imports of crude and manufactured fertilisers increased 53.25% to $8.21 billion during the same period, compared with $5.35 billion a year earlier. Vegetable oil imports rose 11.28% to $9.18 billion.
Disruptions to natural gas supplies also affected domestic fertiliser production. Gas availability for Indian urea plants initially fell to around 60% of normal levels, while urea production declined nearly 27% year-on-year to approximately 1.8 million tonnes in March before supplies subsequently recovered.
The government has absorbed part of the increase in international fertiliser costs through subsidies. Expenditure on urea and nutrient-based fertiliser subsidies rose 20.7% year-on-year to ₹1.03 trillion during April-August, according to the Controller General of Accounts.
Meanwhile, Food Corporation of India data show that central wheat and rice stocks stood at approximately 87 million tonnes on September 1, compared with 70.2 million tonnes a year earlier. Government procurement and foodgrain distribution to more than 800 million beneficiaries provide an additional buffer against shortages of staple cereals.
However, the protection offered by grain reserves does not extend equally to other food categories. According to the Ministry of Statistics and Programme Implementation, retail inflation in September stood at 3.94% for cereals and cereal products, compared with 8.35% for oils and fats, 9.18% for vegetables, tubers and pulses, and 10.75% for fruits and nuts.
Overall food inflation increased to 7.74% in September from 5.97% in August.
The impact is also visible in household food expenditure. According to Crisil Intelligence, the cost of a home-cooked vegetarian thali increased 10% year-on-year to ₹30.8 in September, while a non-vegetarian thali became 6% costlier at ₹59.5. Higher prices of onions, cooking oil, rice and liquefied petroleum gas contributed to the increase.
India’s production outlook matters to global markets
India’s vulnerability extends beyond domestic food prices. The country accounts for around 40% of global rice exports, making its production and export availability important to international markets.
With El Niño creating uncertainty around the next crop cycle, any significant decline in India’s rice output or exportable surplus could tighten global supplies and push prices higher. Crisil expects paddy production to decline by 5-6%, citing lower acreage and weaker yields.
Industry experts warn that the effects of higher energy and fertiliser prices can spread across the food supply chain, affecting irrigation, farm operations, processing, storage and transportation.
Chirag Jain, partner at Grant Thornton Bharat, said higher energy prices increase the cost of fuel, irrigation, transport and other agricultural operations. Fertiliser disruptions can raise input costs and affect farm profitability, with the additional expenses eventually reaching consumers.
He also highlighted gaps in cold-chain infrastructure and post-harvest management, which can increase losses and the cost of delivering perishable foods.
Satyam Shivam Sundaram, partner, strategy and transactions at EY LLP, said the impact on 2027 production would depend on the duration of supply disruptions, whether fertilisers reach farmers before critical application periods and whether higher prices lead to reduced usage.
Bhabesh Hazarika, economist at the National Institute of Public Finance and Policy, said the risks would intensify if the rabi crop were affected, energy and fertiliser prices remained elevated, and higher logistics costs spread across the food supply chain.
Over the next six to 12 months, key indicators will include pulses, edible oils and vegetable prices; rabi sowing and soil moisture; reservoir levels; crude oil and fertiliser prices; the rupee; freight costs; and government decisions on food imports, exports and stock management.
The critical question is whether inflation remains concentrated in a few commodities or spreads across the wider food basket.
For consumers, the distinction between food availability and affordability is becoming increasingly important. Near-record grain supplies may reduce the risk of an immediate cereal shortage, but they cannot fully offset rising production costs, weather uncertainty and disruptions to global trade. The trajectory of food prices will depend not only on how much the world harvests, but also on the cost of producing, moving and delivering that food to households.